

Launching a crypto presale can look deceptively simple from the outside. Create a token, publish a website, announce a price, connect a wallet, attract buyers and wait for capital to arrive.
That description misses most of the real work.
A credible crypto presale is closer to launching a regulated technology startup, a digital financial product, a cybersecurity operation, a fundraising campaign and an online community at the same time. The token is only one component. Behind it sit corporate entities, founders, intellectual property, smart contracts, wallets, compliance systems, banking relationships, treasury controls, token economics, disclosures, marketing rules, data protection, customer support, accounting, security, vesting, liquidity planning and years of obligations that can survive long after the presale closes.
That distinction matters because a presale can fail even when the token contract works perfectly. It can fail because the legal structure is wrong. It can fail because the project sells into a jurisdiction it did not understand. It can fail because the tokenomics make long-term sustainability impossible. It can fail because the team loses treasury access, an administrator wallet is compromised, an affiliate makes unlawful claims, liquidity is too thin, vesting creates a supply shock, or buyers discover that the promises made during fundraising cannot realistically be delivered.
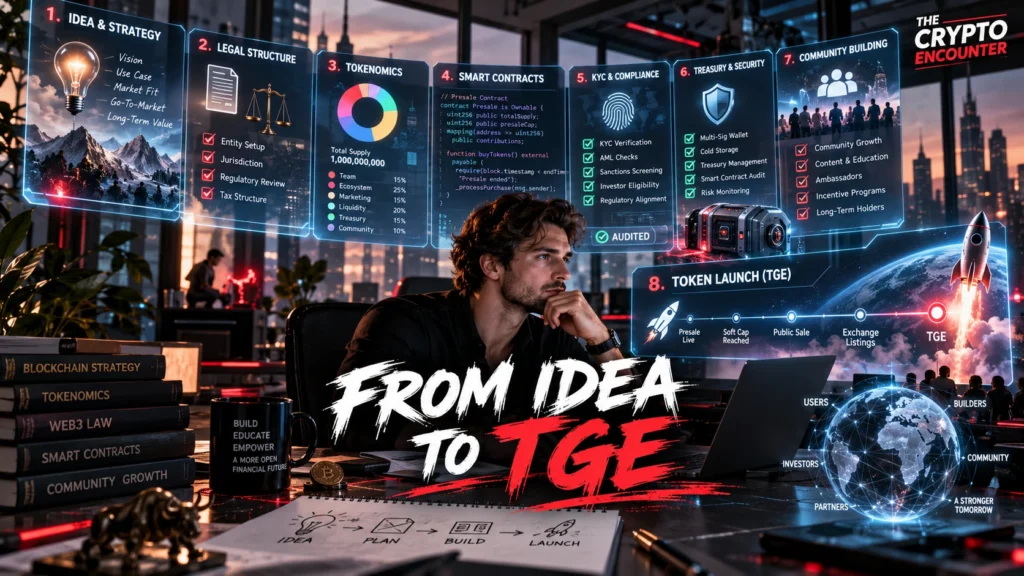
This guide explains the entire lifecycle from the founder’s perspective, from the first idea through the token generation event, or TGE, and into post-launch operations.
It is deliberately detailed because becoming a crypto presale entrepreneur is not principally about learning how to mint a token. It is about learning how to build an organization capable of issuing, selling, securing, accounting for, communicating about and ultimately supporting a digital asset without losing control of the business around it.
Important: This article is educational. Crypto regulation, securities treatment, taxation, licensing, consumer-protection obligations and fundraising laws vary by jurisdiction and by the facts of each project. Nothing in this guide is legal, tax, investment, accounting or regulatory advice. Readers should review The Crypto Encounter’s disclaimer and obtain qualified professional advice before conducting a token offering or accepting funds.
What Is a Crypto Presale?
A crypto presale is an early distribution or sale of tokens before a broader public launch, exchange listing, token generation event or other milestone defined by the project.
The word “presale” is a commercial description. It is not, by itself, a legal classification.
Two projects may both call their fundraising rounds presales while creating entirely different legal relationships. One may sell access to a functional network. Another may offer a token whose value depends heavily on a management team’s future work. A third may structure a private contractual right to receive tokens later. A fourth may distribute tokens without accepting money at all.
That is why a founder should not begin with the question, “How do I sell my token?”
The first question is more fundamental:
What exactly is being created, what rights does it give the holder, what will buyers reasonably expect, and what activity is the issuer actually conducting?
Those answers influence almost everything that follows.
Common presale structures
Projects use several broad fundraising structures, sometimes in combination:
- Private sale: Tokens or contractual rights are offered to a limited group of participants before the public launch.
- Strategic round: Selected investors, ecosystem participants or commercial partners receive an allocation, usually with negotiated restrictions or vesting.
- Community presale: A larger group of participants can purchase before public trading begins.
- Public token sale: Eligible participants are offered tokens under published terms before or around the TGE.
- Launchpad sale: A third-party platform facilitates some combination of fundraising, allocation, KYC and distribution.
- Future-token agreement: Participants fund the project under a contract that may provide a right to receive tokens later. Legal treatment depends heavily on jurisdiction and structure.
- Fair or community distribution: Tokens may be allocated through participation rather than a conventional sale, although a different distribution method does not automatically remove regulatory questions.
Calling one structure a “community round” instead of an “investment round” does not change its legal substance. Regulators, courts, banks and counterparties generally look at the economic reality, rights, representations and activities rather than the marketing label chosen by the issuer.
What Does a Crypto Presale Entrepreneur Actually Build?
A first-time founder may imagine the project as a website plus a token contract. A functioning operation is much broader.
A serious presale normally has at least nine interconnected systems:
| System | What it controls | What can go wrong |
|---|---|---|
| Corporate system | Ownership, contracts, intellectual property, employment and liabilities | The wrong entity signs agreements or receives funds |
| Regulatory system | Token classification, licensing, selling restrictions and disclosures | The project conducts an activity requiring authorization |
| Token system | Supply, utility, allocations, vesting and governance | Economics become unsustainable or misleading |
| Technical system | Blockchain, contracts, sale infrastructure and token distribution | A bug or privileged key compromises the token |
| Security system | Wallets, keys, access, domains and incident response | Funds or administrative privileges are stolen |
| Financial system | Treasury, banking, accounting, reconciliation and budgeting | Funds cannot be accounted for or safely accessed |
| Compliance system | KYC, AML, sanctions, geography and participant records | Prohibited or high-risk participants enter the sale |
| Commercial system | Marketing, PR, community, affiliates and partnerships | Unsupported or unlawful claims reach potential buyers |
| Operational system | Support, reporting, vesting, claims, complaints and post-launch execution | The project raises capital but cannot operate afterward |
The entrepreneurial challenge is coordinating all nine without allowing one to contradict another.
For example, the marketing team cannot promise that tokens are immediately usable if the product team says the network will not function for six months. Tokenomics cannot promise a three-year vesting program if the smart contracts release the allocation after twelve months. A whitepaper cannot claim that the founder has no unilateral control if one founder-controlled wallet can mint unlimited tokens.
Consistency is part of compliance, credibility and product design.
Step 1: Decide Whether the Project Needs a Token at All
The first meaningful tokenomics decision comes before tokenomics exists.
Does the business genuinely need a blockchain token?
A token can make sense when it performs a function that benefits from transferable digital ownership, programmable settlement, decentralized participation, network incentives, on-chain governance, verifiable scarcity, interoperability or access to a blockchain-native system.
It becomes harder to justify when it exists mainly because the founder believes a token will make fundraising easier.
A useful internal exercise is to describe the entire product without mentioning cryptocurrency. Define the customer, problem, product, revenue model, operating costs, competitive landscape and reason users would return.
Then ask what the token adds.
If deleting the token makes the product clearer without destroying an essential feature, the project may have a token problem rather than a token opportunity.
Questions a founder needs to answer before token development
- What problem does the project solve?
- Who experiences that problem?
- Why is a blockchain relevant?
- Why is a transferable token relevant?
- What can the token actually do?
- Can the product function before speculative trading begins?
- What gives users a reason to acquire the token other than expecting the price to rise?
- Who creates demand?
- What creates token supply?
- Can the project survive if token prices fall sharply?
- How is the business funded after the presale?
- What happens when treasury reserves decline?
These questions force the founder to distinguish a business model from a fundraising narrative.
Step 2: Write a Founder-Level Project Thesis Before the Whitepaper
A whitepaper is not the first document a founder needs.
Start with a private project thesis.
This can be relatively short, but it should force the founding team to make decisions that marketing copy normally avoids.
The document should explain:
- the problem;
- the intended users;
- the proposed product;
- why blockchain infrastructure is being used;
- why a token is necessary;
- what network or business behavior gives the token utility;
- how the project expects to generate or preserve operating resources;
- what needs to exist before fundraising;
- what fundraising is intended to finance;
- the people responsible for delivery;
- the most serious technological, regulatory and commercial risks;
- what would cause management to abandon the token model.
The last point is important.
A founder who cannot identify circumstances under which a token should not be launched may already be too emotionally or financially committed to the idea.
Step 3: Build the Project Around a Real Legal Entity
A blockchain address is not a substitute for a company.
A serious project normally needs a legal entity, or sometimes a group of entities, capable of entering contracts, hiring staff, owning intellectual property, engaging professional advisers, opening accounts, paying taxes, maintaining records and bearing legal obligations.
The appropriate structure depends on what the organization actually does.
A project may potentially separate functions among an operating company, token issuer, technology developer, foundation or other vehicle, but creating more companies is not automatically better. Each entity can introduce additional banking, accounting, governance, reporting, tax and administrative obligations.
The structure needs a commercial reason, not merely a diagram that looks sophisticated in a pitch deck.
What founders should establish before accepting money
At minimum, the project’s corporate file may need to establish:
- the legal name of each entity;
- jurisdiction of incorporation;
- registered office;
- shareholders or members;
- directors and authorized signatories;
- ultimate beneficial owners;
- capital structure;
- founder agreements;
- ownership of code and intellectual property;
- employment or contractor relationships;
- authority to issue the token;
- which entity accepts sale proceeds;
- which entity owes obligations to purchasers;
- which entity manages treasury assets;
- how conflicts between entities are resolved.
A common early-stage weakness is allowing developers, designers, founders or contractors to create valuable intellectual property before contracts establish who owns it. If a critical smart contract repository, brand, domain or application is personally owned by somebody who later leaves the team, the issue can become much more expensive than documenting ownership from the beginning.
Step 4: Choose a Jurisdiction Based on Activity, Not a Crypto-Friendly Slogan
There is no universally “best country” for a crypto presale.
A jurisdiction that works well for one project may be unsuitable for another because token characteristics, founder residency, customer geography, banking requirements, licensing obligations, tax treatment and operational activities differ.
A founder evaluating jurisdictions needs to consider several separate questions.
Where is the company incorporated?
This determines part of the project’s corporate and regulatory environment.
Where are the founders actually working?
A company registered in one country does not automatically erase obligations created by management, employees or business activity elsewhere.
Where are purchasers located?
Online fundraising can create cross-border exposure. The company may be incorporated in one place while purchasers connect from dozens of others.
Where are services being provided?
If the project operates an exchange, custody service, transfer service, brokerage, lending activity, payment function or other regulated business, the licensing analysis can become different from the analysis applicable merely to issuing a token.
Where will the money go?
Banking, custody, fiat conversion and treasury operations can determine whether a theoretically attractive corporate structure is usable in practice.
In the United Arab Emirates, for example, crypto regulation is not one undifferentiated national licensing regime. Dubai’s Virtual Assets Regulatory Authority regulates virtual-asset activity across Dubai’s mainland and free zones except DIFC. Its current issuance framework states that entities issuing a virtual asset in the course of business must assess the applicable issuance category, and its guidance includes whitepaper and disclosure requirements. Founders considering Dubai can review the official VARA Virtual Asset Issuance guidance rather than relying on marketing material from incorporation agents.
Abu Dhabi Global Market, DIFC and federal UAE frameworks can involve different authorities and legal considerations. The correct analysis depends on the entity, location and activity.
The same principle applies internationally. “Crypto-friendly” is not a legal category.
Step 5: Determine What the Token Is Before Deciding How to Sell It
Token classification sits near the center of the entire project.
Founders need legal analysis of the token’s characteristics, the transaction through which it is sold and the promises surrounding it.
The distinction between an asset and the way it is offered can matter.
In the United States, the Securities and Exchange Commission issued a new Commission-level interpretation in March 2026 addressing how federal securities laws apply to certain crypto assets and transactions. Among other points, the SEC distinguished categories of crypto assets and addressed circumstances in which a non-security crypto asset can nevertheless become subject to an investment contract through the surrounding transaction. Founders targeting the United States should work from the current SEC interpretation, rather than assuming old ICO-era summaries remain sufficient.
That creates an important practical lesson.
The legal analysis cannot stop at the token’s code.
Authorities may examine representations about profits, managerial effort, promised development, distribution arrangements, rights, control, marketing, functionality and other facts surrounding the sale.
A utility label is not a legal shield
Writing “UTILITY TOKEN” at the top of a whitepaper does not settle its classification.
Neither does adding a disclaimer saying the token is not an investment.
What matters is the substance of the arrangement.
If promotional material spends twenty pages describing future appreciation, exchange listings, investor returns and management’s efforts to increase value, a one-line “utility only” disclaimer may conflict with the project’s own communications.
Step 6: Understand What Changes When You Sell Into the European Union
The European Union provides a useful example of why geographical planning belongs at the beginning rather than the end.
The Markets in Crypto-Assets Regulation, commonly known as MiCA, created a harmonized EU framework covering categories of crypto assets, issuers and crypto-asset service providers while excluding assets already regulated as certain financial instruments and other specified products.
MiCA establishes requirements relevant to public offerings, disclosure, whitepapers, communications and service-provider activity. The exact obligations depend on the type of asset and activity.
Founders considering EU distribution should work from the official MiCA regulation and current national implementation rather than treating Europe as a single unrestricted online market.
The Crypto Encounter has also examined the practical transition toward the MiCA regime in its coverage of MiCA migration and financial-crime compliance.
The broader lesson is global: a website can be visible everywhere even when an offering is not lawfully available everywhere.
Step 7: Create a Jurisdiction Matrix Before Opening the Presale
Instead of using a single global “Buy Now” button with a disclaimer beneath it, sophisticated projects map jurisdictions before launch.
A jurisdiction matrix can classify countries into operational categories such as:
| Category | Possible treatment | Operational implication |
|---|---|---|
| Approved | Offering reviewed and permitted under the project’s framework | Participants may proceed subject to onboarding requirements |
| Conditional | Additional investor status, disclosures or restrictions may apply | Extra verification may be required |
| Restricted | Project does not offer the presale into that location | Geofencing and contractual restrictions may be used |
| Unresolved | Legal treatment has not been sufficiently established | No sale until reviewed |
This is not merely a website feature. It affects advertising, affiliate campaigns, email lists, KYC rules, terms, community moderation and customer-support scripts.
A project that prohibits sales into a country while paying influencers to actively solicit purchasers there has not solved the geographical problem.
Step 8: Map the Regulatory Activities Around the Token
A founder can become so focused on whether the token is a security that other regulated activities receive too little attention.
The business model may also involve:
- custody;
- exchange services;
- money transmission;
- brokerage;
- payment processing;
- transfer and settlement;
- staking services;
- lending;
- portfolio management;
- fiat conversion;
- stablecoin issuance;
- market making;
- financial promotion;
- operating a trading platform.
Each can create separate regulatory questions.
This is one reason copying another project’s structure can be dangerous. Two tokens that appear similar on a chart may sit inside businesses performing different regulated functions.
Step 9: Build AML, KYC and Sanctions Controls Around the Actual Risk
Anti-money laundering and counter-terrorist financing requirements have become a central part of the virtual-asset industry.
The Financial Action Task Force, or FATF, has spent years developing standards for virtual assets and virtual-asset service providers. Its 2026 work continues to emphasize licensing, supervision, risk-based controls and implementation of obligations such as the Travel Rule across relevant regulated activities.
Whether a particular token issuer itself qualifies as a regulated VASP or another regulated entity depends on the structure and jurisdiction. Founders should not automatically assume that either every token project is a VASP or that issuing a token places the project outside AML obligations.
A practical onboarding architecture may include
- identity verification;
- date of birth and address checks where applicable;
- company verification for corporate participants;
- ultimate beneficial ownership checks;
- sanctions screening;
- politically exposed person screening where relevant;
- risk scoring;
- wallet screening where legally or operationally required;
- source-of-funds or source-of-wealth reviews in higher-risk cases;
- jurisdiction checks;
- transaction monitoring;
- manual escalation procedures;
- record retention;
- suspicious-activity procedures where applicable.
The compliance workflow should be defined before customer acquisition begins because compliance can change conversion rates, support requirements and the design of the sale dashboard itself.
Step 10: Verify the Founding Team Before Asking the Public to Trust It
A presale asks participants to trust people who may control treasury assets, contract privileges, product development and future token supply.
That makes founder identity a substantive part of project risk.
The crypto market has also entered an era in which convincing biographies, photographs, voices and even entire teams can be synthetically generated. The Crypto Encounter’s examination of AI-generated crypto teams illustrates why a polished team page is no longer sufficient evidence that accountable people exist behind a project.
A credible team file can establish:
- legal identities;
- roles and responsibilities;
- employment or contractor status;
- relevant professional history;
- conflicts of interest;
- token allocations;
- vesting obligations;
- authority over wallets and smart contracts;
- intellectual-property assignments;
- departure procedures.
Founders should also decide what will be public.
There can be legitimate reasons for privacy, but anonymity changes counterparty risk. Banks, auditors, regulators, professional advisers and sophisticated investors may still require identification even when the public website does not disclose every individual.
Step 11: Design Governance Before Money Creates Conflict
Early teams often operate through friendship and informal consensus. Fundraising changes the stakes.
Before a presale, founders need clarity about who can make which decisions.
Governance questions include:
- Who can alter token parameters?
- Who controls minting privileges?
- Who controls treasury wallets?
- Who can pause contracts?
- Who authorizes spending?
- Who signs exchange agreements?
- Who can appoint advisers?
- Who approves marketing claims?
- Who communicates during a crisis?
- What happens if founders disagree?
- What happens if a signer disappears?
- What happens if a founder resigns?
- Can founder tokens continue vesting after departure?
These questions can feel premature before the project raises money. After money arrives, they become much harder to negotiate.
Step 12: Build Token Utility Before Building Token Hype
Token utility describes what a token actually does inside the product or network.
Possible functions can include access, settlement, network fees, governance, staking, collateral, rewards or participation in a defined digital ecosystem. The function should match the product rather than being inserted because similar tokens use the same vocabulary.
For each proposed function, founders can document:
| Question | Why it matters |
|---|---|
| Who needs the token? | Defines genuine users |
| Why do they need it? | Defines utility |
| When can they use it? | Connects functionality to the roadmap |
| What consumes or locks it? | Explains demand mechanics |
| What creates new supply? | Explains inflation |
| Who controls parameters? | Reveals governance risk |
| Can the system work without it? | Tests whether utility is real |
A token should not require a paragraph of financial speculation to explain why it exists.
Step 13: Build Tokenomics as an Economic System, Not a Pie Chart
Tokenomics is often reduced to a colorful allocation chart. That chart is only the beginning.
A complete tokenomics model needs to connect supply, demand, distribution, incentives, vesting, product behavior, treasury requirements and governance.
Total supply
Define whether supply is fixed, inflationary, deflationary or adjustable.
If additional tokens can be minted, identify who controls that power, under what circumstances and within what limits.
Allocation
Possible allocation groups include:
- public sale;
- private or strategic rounds;
- founders;
- employees;
- advisers;
- ecosystem incentives;
- community programs;
- treasury;
- liquidity;
- partnerships;
- future development.
There is no universal percentage that makes these allocations “correct.”
The central question is whether each allocation can be justified by the project’s economic design and whether supply enters circulation at a pace the ecosystem can realistically absorb.
Circulating supply
Total supply and circulating supply are not the same thing.
A project with one billion tokens may launch with only a small portion available for transfer. Founders therefore need a month-by-month circulating-supply model rather than a static total-supply figure.
Vesting
Vesting can reduce abrupt distribution by releasing allocations over time.
A vesting model needs to define:
- start date;
- cliff;
- release frequency;
- duration;
- beneficiary;
- conditions;
- whether vesting is enforced on-chain or contractually;
- what happens if a contributor leaves.
A marketing page saying “team tokens locked for 24 months” should correspond to an enforceable mechanism, not merely management’s intention.
Step 14: Understand FDV Before Setting a Presale Price
Token price means little without supply.
A project setting a price needs to understand fully diluted valuation, commonly shortened to FDV.
The basic calculation is:
Token price × total token supply = implied fully diluted valuation.
Consider a purely hypothetical example.
If a token has a total supply of 1 billion units and the presale price is $0.05, the implied FDV is $50 million.
If 100 million tokens are sold at that price, the gross amount represented by that allocation would be $5 million if all 100 million were sold at the same price.
That does not mean the project is worth $50 million in a conventional corporate-valuation sense. FDV is a token-market calculation based on price and theoretical total supply.
The example exposes why arbitrary token pricing can be misleading. Calling a token “cheap” because it costs five cents says nothing useful unless supply is also considered.
Presale models can use different pricing structures
- one fixed price;
- multiple fundraising rounds;
- time-based price changes;
- allocation-based tiers;
- auction mechanisms;
- other rules defined by the offering.
Whatever model is used needs to be explainable, technically enforceable and consistent with applicable law and public disclosures.
Step 15: Define the Raise Around a Use-of-Funds Model
The fundraising target should connect to an operating plan.
A project can begin with the activities that must be financed:
- engineering;
- security;
- legal and compliance;
- licenses and corporate administration;
- staff and contractors;
- infrastructure;
- product development;
- audits;
- community operations;
- communications;
- business development;
- treasury reserves;
- accounting and tax;
- liquidity-related requirements where applicable;
- contingency.
Then model how long the capital is intended to support those activities.
The danger of working backward from an attractive fundraising number is that the sale target can become disconnected from execution.
A founder saying “we want to raise $10 million” should be able to explain what materially changes at $10 million that cannot be achieved at $3 million or requires more than $15 million.
Step 16: Define Soft Cap, Hard Cap and Failure Conditions Carefully
Presales often refer to a soft cap and a hard cap.
These expressions need precise definitions.
A hard cap generally describes the maximum amount the sale intends to accept.
A soft cap may describe a minimum funding threshold or internal target, but the consequences of missing it vary between projects. The term itself does not automatically create a refund obligation.
If purchasers are told that funds will be returned when a threshold is not reached, the project needs a practical mechanism for doing so.
That raises operational questions:
- Where are funds held while the threshold remains unresolved?
- Are they segregated?
- Who controls them?
- How are network fees handled?
- What happens when the value of a contributed crypto asset changes?
- What happens if a participant’s original wallet becomes inaccessible?
- What sanctions or KYC checks apply to refunds?
- Who bears fiat conversion costs?
A refund promise is an operational obligation, not marketing decoration.
Step 17: Design the Whitepaper as a Disclosure Document
The crypto industry inherited the term “whitepaper” from technical publishing, but token whitepapers can function as much more than technical explanations.
Depending on jurisdiction and offering structure, formal disclosure requirements may apply.
Even where a particular statutory template is not required, a credible whitepaper can organize the project around verifiable statements.
A comprehensive whitepaper may cover
- project summary;
- problem being addressed;
- product architecture;
- blockchain choice;
- token function;
- total supply;
- allocation;
- vesting;
- sale structure;
- governance;
- team;
- corporate entities;
- roadmap;
- use of proceeds;
- technology risks;
- smart-contract risks;
- market risks;
- liquidity risks;
- regulatory risks;
- custody and wallet risks;
- conflicts of interest;
- geographic restrictions;
- material dependencies;
- legal notices.
The whitepaper should not become a repository for promises nobody owns.
Every roadmap item can be mapped internally to a responsible person, estimated resources, dependencies and status.
Step 18: Separate the Whitepaper From the Legal Documents
A whitepaper does not necessarily replace formal legal documents.
Depending on the project, participants may also encounter:
- presale terms;
- token purchase terms;
- privacy policy;
- cookie notice;
- risk disclosures;
- AML/KYC notices;
- restricted-jurisdiction notices;
- website terms of use;
- refund terms;
- vesting agreements;
- private-sale agreements;
- affiliate agreements;
- adviser agreements;
- employment and contractor agreements.
These documents need to agree with one another.
A whitepaper stating that tokens are non-refundable while the checkout screen promises a seven-day refund can create obvious problems. So can a privacy policy claiming that identity data is not shared with third parties when the project uses external KYC providers.
Step 19: Choose the Blockchain for the Product, Not for Fashion
The blockchain influences user experience, fees, smart-contract development, liquidity, wallet compatibility, security assumptions, tooling and operational complexity.
A founder evaluating networks can examine:
- security model;
- transaction fees;
- transaction throughput;
- finality;
- smart-contract capabilities;
- developer ecosystem;
- wallet availability;
- exchange support;
- bridge dependencies;
- liquidity ecosystem;
- block explorer quality;
- token standards;
- network reliability;
- decentralization characteristics;
- user familiarity.
A cheap network is not automatically better if target users struggle to acquire gas tokens or major infrastructure partners do not support it.
Likewise, deploying across multiple chains can increase reach while multiplying technical and security complexity.
Step 20: Define the Smart-Contract Architecture Before Coding
The token contract is only one part of the technical stack.
A presale may involve multiple contracts controlling different functions.
These can include:
- token issuance;
- sale logic;
- vesting;
- claiming;
- staking;
- governance;
- treasury;
- liquidity;
- access control;
- upgrade mechanisms.
The architecture document should answer basic questions
Can additional tokens be minted?
Can tokens be burned?
Can transfers be paused?
Can addresses be blocked?
Can the contract be upgraded?
Who holds administrative privileges?
Can one private key change critical parameters?
Can presale terms be changed after contributions begin?
How are vesting schedules enforced?
What happens if the sale contract receives an unsupported asset?
How are rounding errors handled?
How does the system respond to an emergency?
These decisions have governance consequences. A technically convenient administrator function may also create a major centralization risk.
Step 21: Avoid Single-Key Control of Critical Assets
A founder’s laptop should not become the single point of failure for millions of dollars in treasury assets or irreversible smart-contract privileges.
Projects can separate functions among different wallets and access policies.
Typical wallet categories can include:
- deployment wallet;
- contract administrator;
- presale receiving wallet;
- operating treasury;
- long-term treasury;
- liquidity wallet;
- vesting wallet;
- community or rewards wallet;
- testing wallet.
Each wallet can have a defined purpose rather than allowing one address to accumulate every authority.
The principle resembles the wallet-separation discipline The Crypto Encounter discusses in The DeFi Wallet Separation Rule. A wallet used frequently and exposed to websites, approvals and transactions carries a different risk profile from one intended to protect long-term reserves.
Step 22: Understand Why Multisignature Treasury Control Matters
A multisignature arrangement can require more than one authorized signer before specified transactions are executed.
That can reduce dependence on a single private key, but multisignature design creates its own operational questions.
Founders need to define:
- number of signers;
- signature threshold;
- who the signers are;
- how geographically concentrated they are;
- what happens when a signer leaves;
- how signer devices are secured;
- how emergency rotation works;
- how signing requests are independently verified;
- whether the multisig itself can upgrade critical contracts.
A three-of-five multisig is not meaningfully distributed if all five keys sit on devices controlled by one person.
Step 23: Treat Token Approvals as a Security Issue
Presale applications may interact with stablecoins, decentralized exchanges and other smart contracts requiring token approvals.
An approval can give another contract permission to spend a user’s tokens. Depending on the allowance, that permission may remain active after the immediate transaction ends.
The Crypto Encounter explains this delayed exposure in The Token Approval You Forgot Can Drain You Later.
Presale interfaces should therefore make approvals understandable rather than hiding them beneath generic buttons.
Users need to know whether they are signing a message, approving a token, transferring funds or executing another on-chain action.
Step 24: Audit More Than the Token Contract
Security review should not stop after somebody confirms that the basic token can transfer from one wallet to another.
The relevant attack surface can include:
- token contracts;
- sale contracts;
- vesting contracts;
- claim contracts;
- admin privileges;
- upgrade mechanisms;
- front-end application;
- APIs;
- database;
- KYC integration;
- cloud accounts;
- domain registrar;
- DNS;
- email;
- social accounts;
- code repositories;
- developer credentials;
- staff devices;
- treasury wallets.
A secure blockchain does not guarantee a secure project. The Crypto Encounter’s guide to why crypto can be secure without the user being safe addresses precisely this gap between protocol integrity and operational safety.
Step 25: Conduct a Smart-Contract Audit Before Mainnet Exposure
A professional audit can examine contract logic, permissions, economic assumptions and known classes of vulnerabilities.
An audit should not be treated as a security certificate.
Auditors review a defined codebase at a defined time. Code can later change. Dependencies can change. New attack techniques can emerge. Privileged administrators can misuse otherwise audited functions. A secure contract can also be paired with a compromised frontend.
Audit readiness improves when the development team provides
- documented architecture;
- complete repositories;
- compiler and dependency information;
- test coverage;
- deployment procedures;
- privilege maps;
- known assumptions;
- expected invariants;
- previous audit findings;
- clear remediation status.
If a project changes audited code afterward, the public should not be left with the impression that the new version is necessarily covered by the old report.
Step 26: Test the Entire Sale on a Test Network
A token sale should be rehearsed as a system.
Test cases can simulate:
- first purchase;
- minimum purchase;
- maximum purchase;
- multiple purchases by one wallet;
- sale cap reached;
- sale closing;
- unsupported network;
- wrong token;
- failed transaction;
- high gas conditions;
- KYC pending;
- KYC rejection;
- restricted jurisdiction;
- vesting calculation;
- claim;
- refund;
- admin-key rotation;
- website outage;
- API outage;
- chain congestion.
The point is to discover contradictions while the money is fictional.
Step 27: Build the Presale Website as a Financially Sensitive Application
A presale website is not an ordinary marketing landing page.
It may ask users to connect wallets, sign messages, submit personal documents, make payments and rely on contract addresses displayed in the interface.
The application therefore sits directly in the transaction path.
A serious sale interface may need to show
- legal issuer;
- official domain;
- token name;
- ticker;
- blockchain;
- verified contract address;
- sale price;
- accepted assets;
- minimum and maximum contributions;
- sale opening and closing rules;
- allocation status;
- vesting rules;
- claim procedure;
- geographic restrictions;
- KYC status;
- transaction history;
- risk disclosures;
- official support channels.
Users should not need to trust a Telegram administrator for the contract address.
Step 28: Harden the Domain, Email and Social Accounts
One compromised social account can redirect an entire community to a malicious sale page.
Operational security therefore extends beyond code.
A project can establish controls around:
- registrar access;
- domain locks;
- DNS changes;
- administrator accounts;
- hardware-backed authentication where available;
- password management;
- email recovery methods;
- social-media account ownership;
- staff access removal;
- phishing-resistant internal procedures;
- production deployment privileges.
The project’s security culture also matters. A strong technical setup can still fail when one person approves a fraudulent login or reveals a recovery credential.
The Crypto Encounter’s crypto safety checklist provides a useful illustration of why links, devices, wallets, approvals and human behavior need to be considered together.
Step 29: Create a Treasury Policy Before Receiving the First Contribution
Fundraising creates a new problem immediately: the project now has assets to protect and account for.
A treasury policy can define:
- approved receiving addresses;
- approved assets;
- signing authority;
- multisignature requirements;
- operating-wallet limits;
- long-term custody arrangements;
- conversion authority;
- counterparty exposure;
- exchange exposure;
- reconciliation;
- transaction documentation;
- emergency controls.
Holding all presale proceeds in whichever cryptocurrency purchasers happened to use can expose the project’s operating budget to market volatility.
Moving everything immediately onto one centralized exchange creates another concentration of risk.
The Crypto Encounter’s analysis of why regulated exchanges are not automatically risk-free explains why regulation does not remove custody, solvency, liquidity or operational exposure.
Step 30: Know What an Exchange Balance Represents
When project funds are deposited with a centralized platform, the project usually does not control the private keys associated with the exchange’s underlying wallets.
Instead, it relies on the platform’s systems, legal arrangements and withdrawal infrastructure.
This distinction is examined in The Crypto Encounter’s guide explaining why an exchange balance is not the same as direct crypto custody.
A treasury architecture can therefore distinguish between funds required for short-term operating transactions and strategic reserves whose custody demands a different risk model.
Step 31: Build Accounting Around Every Movement of Value
Blockchain transparency does not remove the need for accounting.
Every contribution can generate questions about:
- date and time;
- asset received;
- fiat value at the relevant accounting point;
- wallet address;
- participant;
- jurisdiction;
- tokens allocated;
- vesting status;
- refund status;
- transaction fee;
- subsequent conversion;
- tax treatment;
- financial-statement classification.
A block explorer can show that a transaction happened. It does not necessarily explain why it happened, who authorized it, how it should be classified or which contractual obligation it satisfied.
The project therefore needs reconciliation between blockchain records, customer records, bank records, contracts and accounting systems.
Step 32: Solve Banking Before the Presale, Not After It
A project can successfully raise crypto and still discover that ordinary corporate expenses require fiat banking.
Employees, lawyers, auditors, developers, regulators, landlords, insurance providers and tax authorities may not accept payment in the assets collected during the sale.
Bank onboarding can require substantial information about:
- beneficial owners;
- business model;
- token;
- regulatory status;
- expected transaction volumes;
- source of funds;
- customer geography;
- compliance controls;
- exchanges used;
- contracts and counterparties.
The corporate structure should therefore be tested against real operational banking needs before the organization depends on presale proceeds.
Step 33: Design the Participant Journey End to End
The customer journey begins before the blockchain transaction and continues long after it.
A complete journey might look like this:
- User discovers the project.
- User verifies the official domain.
- User reads the project disclosures.
- User creates an account if required.
- User completes eligibility checks.
- User completes KYC or KYB where applicable.
- User accepts relevant terms.
- User connects or verifies a wallet.
- User selects a permitted contribution method.
- User sees the applicable allocation and price.
- User confirms the transaction.
- Backend and blockchain records reconcile.
- User receives confirmation.
- Allocation appears in the dashboard.
- Vesting or claim rules become visible.
- User receives legitimate project updates.
- User claims or receives tokens according to the published process.
Every handoff can create confusion or fraud risk.
That makes support documentation part of product design.
Step 34: Build Data Protection Into KYC Operations
KYC creates a database of highly sensitive personal information.
The project may collect passports, addresses, identity numbers, photographs, corporate documents and wallet information.
That information can create obligations under privacy and data-protection laws depending on the jurisdictions involved.
Founders need to understand:
- what information is collected;
- why it is collected;
- who processes it;
- where it is stored;
- how long it is retained;
- who can access it;
- what happens after the relationship ends;
- how breaches are handled;
- how participants exercise applicable data rights.
“We use KYC” should never mean “we upload passports into a shared folder.”
Step 35: Plan Marketing Around What You Can Prove
Presale marketing carries unusual risk because promotional language can affect both consumer perception and regulatory analysis.
A project’s marketing system should distinguish between:
- verified facts;
- project plans;
- forward-looking goals;
- third-party opinions;
- market data;
- commercial partnerships;
- paid promotion.
The Crypto Encounter’s own editorial standards reject unsupported promises, misleading investment claims and promotional material presented as independent reporting. A token founder benefits from applying the same discipline to project communications.
Claims that need particular scrutiny include
- guaranteed returns;
- guaranteed exchange listings;
- guaranteed price targets;
- “risk-free” language;
- unsupported user numbers;
- unverified partnerships;
- fabricated endorsements;
- fake media coverage;
- false scarcity;
- invented audit claims;
- misleading fundraising totals.
Marketing becomes stronger when it has evidence behind it.
Step 36: Build a Claim Register for the Marketing Team
One practical governance mechanism is a claim register.
It lists important statements the project is allowed to make and the evidence supporting each one.
| Claim | Evidence | Status | Owner |
|---|---|---|---|
| “Contract audited” | Final audit report covering deployed version | Approved after verification | Security lead |
| “Partnership with Company X” | Executed agreement or authorized confirmation | Approved only after consent | Business development |
| “Product live” | Accessible working production system | Approved after deployment | Product lead |
| “Team tokens locked” | Enforceable vesting contract or agreement | Approved after verification | Token operations |
This makes editorial quality machine-actionable. Marketing, PR, community managers and affiliates can work from the same source of truth instead of improvising claims.
Step 37: Treat Influencers and Affiliates as Part of the Compliance Surface
A project cannot assume that responsibility ends when a promotional agency or influencer receives a campaign brief.
Paid promoters may make exaggerated claims, conceal compensation, target restricted geographies or describe speculative outcomes as certainties.
An affiliate program therefore needs governance around:
- permitted jurisdictions;
- approved claims;
- prohibited claims;
- compensation disclosure;
- brand impersonation;
- paid-media rules;
- use of project logos;
- monitoring;
- termination rights;
- record keeping.
The project should know who is speaking on its behalf.
Step 38: Build Community Infrastructure Before Traffic Arrives
Telegram, Discord and social networks can become the public support desk during a presale.
They can also become an attack surface.
Scammers routinely impersonate administrators, create fake support accounts, distribute fraudulent contract addresses and direct users to phishing pages.
Community operations can establish simple immutable rules
- Admins never request seed phrases.
- Admins never request private keys.
- Official contract addresses are published in defined locations.
- Support does not initiate private messages where that rule is operationally possible.
- Sale links come from the official domain.
- Critical announcements are cross-posted through verified channels.
- Compromised channels trigger a predefined incident process.
Consistency reduces the opportunities scammers exploit.
Step 39: Build the Brand Around Verifiability
A first presale often has no reputation history.
That means trust needs to come from evidence.
Useful trust signals can include:
- identifiable legal entities;
- verifiable team members;
- working products;
- public repositories where appropriate;
- clear contracts;
- audits;
- transparent token allocations;
- on-chain vesting;
- consistent disclosures;
- documented partnerships;
- realistic timelines;
- visible correction of errors.
The strongest trust strategy is usually less theatrical than the weakest one.
Step 40: Create a Data Room Before Serious Due Diligence Begins
Partners, investors, exchanges, banks, auditors and advisers may request overlapping information.
A controlled data room can organize documents such as:
- certificate of incorporation;
- constitutional documents;
- ownership records;
- beneficial ownership information;
- board resolutions;
- legal opinions or memoranda where appropriate;
- tokenomics model;
- whitepaper;
- financial model;
- budget;
- team agreements;
- IP assignments;
- smart-contract reports;
- security policies;
- compliance policies;
- vendor agreements;
- material partnerships;
- roadmap evidence.
Access should be controlled because some documents will contain sensitive personal, commercial or security information.
Step 41: Separate a Product Roadmap From a Fundraising Roadmap
A presale campaign can create the illusion that fundraising itself is progress.
It is not.
A commercial roadmap might track:
- website launch;
- community growth;
- presale opening;
- fundraising milestones;
- campaigns;
- TGE;
- listing discussions.
A product roadmap tracks different things:
- architecture;
- prototype;
- testnet;
- security review;
- mainnet;
- integrations;
- user testing;
- feature releases;
- reliability;
- technical debt.
The two schedules should connect, but they should not be confused.
Step 42: Do Not Promise Exchange Listings You Do Not Control
Exchange listings are often treated as a climax in presale marketing.
A founder needs to distinguish aspiration from confirmation.
A project may apply to an exchange. It may enter discussions. It may satisfy preliminary requirements. None of these necessarily means a listing is guaranteed.
A confirmed listing should be described according to what the relevant parties have actually authorized for public disclosure.
Fake listing announcements can create reputational, contractual and potentially regulatory problems.
Step 43: Understand DEX Liquidity Before TGE
Decentralized exchange trading requires liquidity.
A liquidity pool generally contains the project token paired with another asset. The relative balances and automated-market-maker formula help determine the trading price.
If liquidity is shallow, even modest orders can cause substantial price movement.
Founders therefore need to understand:
- initial token amount;
- paired asset amount;
- initial pool price;
- price impact;
- slippage;
- liquidity-provider tokens or positions;
- who controls those positions;
- whether liquidity is locked or otherwise restricted;
- how future liquidity is managed.
Liquidity is not merely a marketing badge saying “DEX live.”
Step 44: Build a TGE Runbook Before TGE Day
The token generation event is one of the worst possible times to decide who is responsible for what.
A written runbook can define the sequence.
Before the event
- verify deployment code;
- verify contract addresses;
- verify chain configuration;
- confirm privileged roles;
- confirm treasury addresses;
- confirm vesting data;
- reconcile presale allocations;
- finalize claim interface;
- test user instructions;
- freeze unauthorized website changes;
- prepare support staffing;
- prepare security monitoring;
- prepare incident communications.
During the event
- monitor contracts;
- monitor infrastructure;
- monitor official social channels;
- monitor impersonation attempts;
- track support issues;
- reconcile distribution;
- record material decisions.
After the event
- verify distribution totals;
- verify vesting;
- reconcile remaining supply;
- publish accurate addresses;
- resolve failed claims;
- review incidents;
- update documentation where appropriate.
Step 45: Test the Claim Process From the User’s Perspective
Projects sometimes spend months designing a presale and far less time testing how participants actually receive their tokens.
The claim process may need to answer:
- When can tokens be claimed?
- Which network is required?
- Who pays gas?
- Can tokens be claimed in portions?
- What happens to unclaimed allocations?
- What happens if a participant changed wallets?
- What happens when a transaction fails?
- How is vesting displayed?
- How are compromised wallets handled?
- What evidence does support require?
Changing a beneficiary wallet can itself be a high-risk procedure because attackers may attempt to redirect legitimate allocations.
Step 46: Prepare for Phishing Before the Claim Window Opens
A token claim is a natural phishing opportunity.
Users expect to connect wallets and sign transactions, which makes fraudulent “claim now” pages more convincing.
The project should communicate the legitimate procedure before scammers define it first.
Security guidance can specify:
- official domain;
- official claim page;
- correct network;
- official contract address;
- actions the legitimate process will never request;
- support channels;
- how to report impersonation.
The basic principle remains the same throughout crypto: valid cryptography cannot rescue a user who was deceived into authorizing the wrong action.
Step 47: Plan for Unlocks Before the Market Has to Absorb Them
Vesting schedules eventually become circulating supply.
A project should maintain an unlock calendar showing how much supply becomes transferable over time.
This matters operationally because large unlocks can affect:
- circulating supply;
- community expectations;
- treasury planning;
- employee incentives;
- liquidity;
- governance concentration;
- reporting.
Founders need to understand not only how tokens are allocated at launch but how ownership evolves twelve, twenty-four and thirty-six months later.
Step 48: Build Post-Presale Reporting Into the Original Plan
The end of fundraising is the beginning of accountability.
A project may need to communicate material developments around:
- product milestones;
- security incidents;
- contract changes;
- treasury use;
- token supply;
- vesting;
- governance;
- partnerships;
- regulatory developments;
- changes to leadership;
- roadmap delays.
Transparency does not require broadcasting commercially sensitive information or weakening security. It does require avoiding the situation where fundraising communication is constant while operational communication disappears after the sale.
Step 49: Create an Incident-Response Plan Before You Need One
Crypto incidents move quickly because blockchain transactions can be irreversible and misinformation spreads immediately.
An incident plan can define response procedures for:
- contract exploit;
- private-key compromise;
- treasury theft;
- website compromise;
- domain hijacking;
- social-account compromise;
- KYC data breach;
- fraudulent token;
- fake support accounts;
- incorrect token distribution;
- critical smart-contract bug;
- service-provider failure.
Every incident needs clear authority
Who detects it?
Who can pause systems?
Who contacts technical partners?
Who contacts counsel?
Who informs users?
Who preserves logs and evidence?
Who speaks publicly?
Who decides when service resumes?
The middle of an attack is a poor time to negotiate those roles.
Step 50: Assume Human Error Will Be Part of the Threat Model
Security planning often emphasizes sophisticated hackers while ignoring ordinary mistakes.
Real losses can begin with:
- a copied address;
- a malicious browser extension;
- a compromised email;
- a fake video call;
- a reused password;
- a fraudulent support request;
- an accidental signature;
- a cloud backup containing credentials;
- a developer committing a secret to a repository;
- a founder sending funds on the wrong chain.
The system should be designed so that one ordinary mistake does not automatically become a catastrophic loss.
Step 51: Separate Business Continuity From Founder Availability
A company cannot safely depend on one founder being awake, reachable and in possession of one device.
Business continuity can address:
- backup signers;
- document access;
- source-code access;
- bank authority;
- domain ownership;
- social ownership;
- critical vendor accounts;
- recovery procedures;
- succession;
- emergency contacts.
Key-person risk is particularly serious when a founder controls both technical and financial infrastructure.
Step 52: Build a Lean Team Around Functions, Not Titles
An early project does not necessarily need a large headcount. It does need clear ownership of essential functions.
Those functions include:
- founder or executive leadership;
- product;
- blockchain engineering;
- security;
- legal and compliance;
- finance and treasury;
- marketing and communications;
- community operations;
- business development;
- customer support.
One person may initially cover more than one function, but the organization should know when conflicts of interest or workload make that unsafe.
For example, the developer who wrote a contract should not be treated as the only independent security reviewer of that contract.
Step 53: Budget for the Invisible Work
First-time founders often budget for development and advertising because those costs are visible.
The expensive surprises may sit elsewhere.
Pre-launch cost categories can include
- corporate formation;
- legal analysis;
- regulatory applications;
- accounting;
- tax advice;
- smart-contract engineering;
- security audit;
- KYC and AML infrastructure;
- data protection;
- hosting and technical infrastructure;
- website and application development;
- design;
- communications;
- community moderation;
- support;
- insurance where available and appropriate;
- banking and payments;
- post-launch maintenance.
There is no responsible universal number for how much a presale costs because the range changes dramatically according to jurisdiction, product complexity, licensing requirements, codebase, fundraising model and internal capabilities.
The useful budgeting principle is to identify dependencies before marketing commits the project to a launch date.
Step 54: Use a Stage-Gate Model Instead of Racing Toward Launch
A presale becomes easier to control when each stage has exit criteria.
| Gate | Question | Examples of evidence |
|---|---|---|
| Concept | Does the token have a defensible function? | Project thesis and product architecture |
| Corporate | Does an accountable legal organization exist? | Entity documents and authority matrix |
| Legal | Can the proposed offering proceed under defined conditions? | Legal and compliance analysis |
| Economics | Are supply and incentives coherent? | Tokenomics model and unlock schedule |
| Technical | Does the system work? | Testnet, tests and deployment plan |
| Security | Are critical risks understood and remediated? | Audit and security review |
| Operations | Can users be onboarded and supported? | KYC, dashboard, support and treasury workflows |
| Launch | Is every public claim supported? | Final claim register and launch review |
A failed gate should delay the project rather than be hidden by a louder marketing campaign.
Step 55: Build a 90-Day Pre-Presale Workstream
Project timelines vary substantially, and regulated structures can take far longer than ninety days. Still, a 90-day workstream can help founders understand which activities need to run in parallel.
Days 1-15: definition
- Finalize project thesis.
- Define product problem and target users.
- Determine why the token exists.
- Identify founders and key contributors.
- Create preliminary token architecture.
- Identify target jurisdictions.
- Begin regulatory and legal analysis.
Days 16-30: structure
- Establish appropriate corporate architecture.
- Document ownership and authority.
- Assign intellectual property.
- Build first tokenomics model.
- Create treasury model.
- Map participant eligibility.
- Plan KYC and AML workflows.
- Begin banking and financial infrastructure work.
Days 31-45: build
- Develop token contracts.
- Develop sale infrastructure.
- Create website and dashboard.
- Draft whitepaper.
- Draft terms and disclosures.
- Create security architecture.
- Set up operational wallets.
- Build accounting and reconciliation process.
Days 46-60: test
- Deploy to test environment.
- Run purchase simulations.
- Test KYC flow.
- Test allocation and vesting.
- Test administrative functions.
- Test failure states.
- Review website claims.
- Prepare audit package.
Days 61-75: verify
- Complete relevant security reviews.
- Remediate findings.
- Re-test contracts.
- Verify legal documents.
- Verify compliance controls.
- Verify tokenomics calculations.
- Train community and support personnel.
- Finalize crisis procedures.
Days 76-90: launch readiness
- Complete final go/no-go review.
- Verify deployed addresses.
- Verify treasury permissions.
- Publish approved disclosures.
- Activate support monitoring.
- Activate security monitoring.
- Launch only after unresolved critical issues are closed.
This is a sequence model, not a promise that a compliant launch can be completed in ninety days.
Step 56: Know the Difference Between a Presale Dashboard and a Real Back Office
The front-end dashboard shows the customer what is happening.
The back office tells the company what is happening.
Internal operations may need to track:
- participant ID;
- KYC status;
- jurisdiction;
- wallet;
- contributions;
- token allocation;
- price round;
- refund status;
- vesting;
- support history;
- manual adjustments;
- compliance escalation;
- transaction hashes.
Every manual adjustment should be attributable to an authorized person and supported by an audit trail.
Step 57: Establish a Single Source of Truth for Presale Numbers
Nothing damages credibility faster than contradictory fundraising numbers.
The website says $4.2 million.
The press release says $4.6 million.
The community manager says $5 million.
The blockchain shows something else.
This can happen because different teams count pending purchases, bonuses, fiat commitments, cancelled allocations and crypto value differently.
The project needs one written methodology defining:
- what counts as funds raised;
- how crypto is converted into reporting currency;
- how refunds are treated;
- how unpaid commitments are treated;
- how bonuses are treated;
- how date cutoffs work;
- who can publish the figure.
A fundraising figure is a factual claim. It should be reproducible.
Step 58: Distinguish Money Raised From Tokens Sold
These are not interchangeable metrics.
A project can sell tokens at multiple prices. The number of tokens allocated therefore cannot be converted into money raised using one arbitrary price.
Likewise, token bonuses can increase allocations without increasing cash received.
Reporting should distinguish:
- gross contributions;
- refunds;
- net proceeds;
- tokens allocated;
- bonus tokens;
- unsold tokens;
- vested versus unvested allocations.
Step 59: Decide What Happens to Unsold Tokens Before the Sale Begins
Unsold tokens create both economic and credibility questions.
Possible treatment can include burning, treasury retention, future ecosystem use or another disclosed mechanism.
The project should determine the approach in advance because changing the treatment later can alter expected supply.
If the team markets scarcity based on one assumption and later changes that assumption, participants may reasonably question the original representation.
Step 60: Make the Roadmap Measurable
“Global expansion,” “ecosystem growth,” “major partnerships” and “mass adoption” sound ambitious but are difficult to audit.
A stronger roadmap uses milestones that can be independently recognized.
Examples include:
- testnet released;
- mainnet released;
- specific product module launched;
- defined API available;
- security audit completed;
- governance functionality activated;
- specified integration completed.
A roadmap should also identify dependencies and uncertainty rather than pretending every quarter is guaranteed.
Step 61: Prepare the Organization for Due Diligence From Skeptical Users
Legitimate users will ask difficult questions.
Who owns the company?
Where is it registered?
Who controls the treasury?
Can the token supply increase?
Are founder tokens locked?
Has the exact deployed contract been audited?
What happens if the project fails?
What happens if the founder leaves?
Are partnerships verifiable?
Who owns the liquidity?
These questions are not attacks. They are part of a healthier market.
Step 62: Do Not Confuse Community Size With Product Demand
A project can accumulate hundreds of thousands of social followers without developing a meaningful user base.
Presale marketing metrics can therefore be divided into different categories.
Attention metrics
- impressions;
- followers;
- video views;
- website sessions.
Intent metrics
- whitepaper reads;
- qualified registrations;
- wallet connections;
- KYC starts;
- KYC completions.
Transaction metrics
- eligible contributors;
- completed purchases;
- average contribution;
- refunds;
- repeat participation where permitted.
Product metrics
- active users;
- transactions;
- retention;
- usage of actual token utility;
- developer activity where relevant.
The last category is what eventually determines whether the project becomes more than a fundraising campaign.
Step 63: Build Customer Support for Financially Sensitive Problems
A presale support team may face questions involving lost money, failed transactions, identity verification and compromised wallets.
Support personnel need defined boundaries.
They should know how to handle:
- pending blockchain transactions;
- wrong-network deposits;
- duplicate payments;
- KYC problems;
- allocation discrepancies;
- wallet changes;
- claim failures;
- refund requests;
- security incidents;
- suspected impersonation.
Support should never improvise access to private keys or ask users for recovery phrases.
Step 64: Document Every Privileged Smart-Contract Function
Privileged functions deserve special attention because they define what administrators can change after deployment.
A privilege register can list:
- function;
- contract;
- authorized role;
- controlling wallet;
- multisig threshold;
- timelock if any;
- business purpose;
- public disclosure status.
This makes it possible to compare technical reality with public claims about decentralization or control.
Step 65: Avoid Unlimited Administrative Power Without Clear Disclosure
An upgradeable smart contract can be useful because defects may need to be corrected.
It can also give administrators substantial power over users.
The same applies to minting, pausing, blacklisting and fee changes.
These capabilities are not automatically improper. The problem begins when the project has them while communicating as though nobody can alter the system.
Technical control and public disclosure should match.
Step 66: Maintain Version Control Across Code and Public Documents
A presale evolves quickly.
Tokenomics change.
Contracts change.
Terms change.
Whitepapers change.
Roadmaps change.
If the project cannot identify which version was effective at a particular time, disputes become harder to resolve.
Version-controlled records can cover:
- whitepaper;
- tokenomics;
- terms;
- risk disclosures;
- contract source code;
- deployment addresses;
- audit reports;
- website claims;
- marketing materials.
Step 67: Build a Correction Policy for the Project
Projects make mistakes.
The credibility test is what happens next.
A correction process can answer:
- Who receives reports of inaccurate information?
- Who verifies the issue?
- Who can amend public materials?
- When is a historical version retained?
- When must participants be directly notified?
- How are material changes documented?
Quietly rewriting a major term after buyers acted on the old version creates a different problem from transparently correcting a typo.
Step 68: Understand the Presale Red Flags Experienced Buyers Look For
Founders benefit from evaluating their own project as a skeptical outsider would.
Common warning signs include:
- anonymous or unverifiable team;
- copied whitepaper;
- no legal entity;
- fake partnerships;
- guaranteed profits;
- unverifiable fundraising numbers;
- contract code that does not match disclosures;
- unlimited mint authority;
- no meaningful vesting;
- single-wallet treasury control;
- no working product;
- extreme marketing pressure;
- fake countdown resets;
- undisclosed influencer compensation;
- unclear use of proceeds;
- no explanation of liquidity;
- missing risk disclosures;
- contradictory token supply figures.
If a legitimate project accidentally looks like a scam, that is still a business problem.
Step 69: Never Let Urgency Replace Verification
Artificial urgency is especially dangerous in crypto because transactions may be irreversible.
Countdown timers can be legitimate when they correspond to real sale rules. They become deceptive when the timer simply resets after reaching zero.
The same applies to claims such as:
- “last chance”;
- “almost sold out”;
- “price increases tonight”;
- “listing confirmed”;
- “whales accumulating”;
- “guaranteed 100x.”
Any factual scarcity or timing claim should be capable of verification.
Step 70: Do Not Build a Business That Requires the Token Price to Rise
This is one of the most important sustainability tests.
Ask what happens if the token trades below the presale price for twelve months.
Can the company still pay staff?
Can development continue?
Can infrastructure bills be paid?
Does the product still solve a problem?
Do users still need the token?
If the answer to every operational question depends on rising token prices, the project has mixed its business model with market speculation.
Step 71: Define What Success Means Beyond the Raise
Presale success is frequently reported as money raised.
A more complete scorecard can include:
- product delivered;
- users retained;
- token utility used;
- security incidents avoided or resolved;
- regulatory obligations met;
- treasury runway;
- roadmap completion;
- developer ecosystem;
- community retention;
- commercial revenue;
- quality of governance.
A project that raises a large amount and fails to build anything is not a stronger company than one that raises less and creates a durable product.
The Complete Crypto Presale Lifecycle at a Glance
| Phase | Core objective | Main output |
|---|---|---|
| 1. Concept | Prove a token is relevant | Founder thesis |
| 2. Product | Define what users receive | Product architecture |
| 3. Corporate | Create accountable ownership | Legal entities and governance |
| 4. Regulatory | Determine permitted activity | Jurisdiction and compliance framework |
| 5. Tokenomics | Design economic behavior | Supply, allocation and vesting model |
| 6. Documentation | Explain rights, risks and structure | Whitepaper and legal documents |
| 7. Engineering | Build token and sale infrastructure | Contracts and application |
| 8. Security | Reduce technical and operational risk | Testing, audits and controls |
| 9. Finance | Protect and account for capital | Treasury, banking and accounting |
| 10. Onboarding | Control participant eligibility | KYC, AML and sale workflows |
| 11. Communications | Acquire users without misleading them | Marketing and community system |
| 12. Presale | Execute fundraising | Verified allocations and proceeds |
| 13. TGE | Generate and distribute tokens safely | Token launch and claims |
| 14. Liquidity | Enable market functionality where intended | Exchange or DEX infrastructure |
| 15. Post-launch | Deliver the project | Product, reporting and governance |
The Founder’s Final Pre-Presale Checklist
Corporate
- Legal entities established
- Beneficial ownership documented
- Founder relationships documented
- IP owned by the correct entity
- Signing authority established
Regulatory
- Token and transaction structure reviewed
- Target jurisdictions identified
- Restricted jurisdictions defined
- Licensing implications reviewed
- Marketing restrictions reviewed
- AML/KYC obligations mapped
Tokenomics
- Total supply confirmed
- Minting policy confirmed
- Allocations reconciled to 100%
- Vesting documented
- Unlock schedule modeled
- Presale pricing mathematically consistent
- Unsold-token treatment defined
Technology
- Contracts tested
- Deployment procedure documented
- Admin roles mapped
- Contracts independently reviewed where appropriate
- Frontend tested
- Dashboard reconciles correctly
- Claim mechanism tested
Security
- Critical wallets separated
- Private-key policies established
- Multisig configured where appropriate
- Domain access protected
- Email protected
- Social accounts protected
- Incident plan documented
Finance
- Official receiving wallets identified
- Treasury policy approved
- Banking path understood
- Accounting method established
- Reconciliation tested
- Operating runway modeled
Participant operations
- Eligibility rules implemented
- KYC flow tested where applicable
- Sanctions controls implemented where required
- Terms acceptance recorded
- Support process established
- Refund rules operationally possible
Communications
- Whitepaper consistent with code
- Website consistent with terms
- Partnership claims verified
- Audit claims verified
- Fundraising methodology defined
- Influencer guidance documented
- Risk disclosures visible
Frequently Asked Questions About Launching a Crypto Presale
Can anyone create a cryptocurrency token?
From a purely technical perspective, widely used blockchain standards have made basic token creation relatively accessible. Creating the token, however, is only a small part of launching a lawful and operationally credible project. Issuance, fundraising, marketing, custody, money transmission, financial promotion and other activities can create legal or regulatory obligations depending on the jurisdiction and structure.
Do I need a company before launching a presale?
A serious commercial project generally needs to identify the legal person responsible for contracts, intellectual property, fundraising, employment, compliance and liabilities. The exact entity structure depends on jurisdiction and activities. Accepting public funds before clarifying who legally operates the project can create significant contractual, banking, tax and compliance problems.
Is a utility token automatically exempt from securities laws?
No. A “utility” label does not by itself determine regulatory treatment. Authorities can examine the token’s actual characteristics as well as the economic reality and circumstances of the transaction through which it is offered or sold. Legal analysis needs to consider the entire arrangement.
Can a crypto presale accept buyers from every country?
Not automatically. Online accessibility does not mean an offering is lawfully available in every jurisdiction. Projects may need to restrict particular locations or participant categories and comply with jurisdiction-specific offering, marketing, AML, consumer-protection and financial-services rules.
Do all crypto presales require KYC?
The applicable requirements depend on the activities, structure and jurisdictions involved. AML and KYC obligations can arise under laws governing virtual-asset service providers, financial institutions, token offerings, money transmission or other regulated activity. Even where a particular rule does not apply directly, counterparties such as banks and exchanges may impose their own onboarding requirements.
How much does it cost to launch a crypto presale?
There is no credible universal figure. Costs vary according to corporate jurisdiction, legal complexity, licensing, smart-contract development, security audits, KYC infrastructure, product development, team structure, marketing, treasury operations and post-launch obligations. A simple token can be inexpensive to create technically while a compliant commercial launch can require substantially greater resources.
How long does it take to launch a token presale?
The technical act of deploying a token can be fast. Building a legally reviewed, secure and operational presale can take much longer. Corporate formation, licensing, banking, legal work, audits and product development can determine the real timeline. Projects should not set public launch dates before understanding those dependencies.
What is the difference between a private sale and a public presale?
A private sale is generally directed to a limited or defined set of participants, while a public presale is made available more broadly. The precise legal meaning of “private” and “public” depends on the relevant legal framework. Simply placing a password on a page does not necessarily transform a broadly marketed offering into a legally private transaction.
What is a token generation event?
A token generation event, commonly called a TGE, is the point at which a project’s tokens are created, activated, distributed or otherwise become operational according to the project’s structure. It may coincide with claims, transfers or exchange activity, but projects can define different sequences. Public documentation should explain exactly what TGE means for that particular project.
What is the difference between token price and FDV?
Token price is the price assigned to one unit. Fully diluted valuation multiplies that price by the total token supply. A token costing a few cents can still imply a very large FDV if billions of units exist. Looking only at the unit price can therefore create a misleading impression of relative value.
Should founder tokens be vested?
Vesting is one mechanism projects use to control when allocations become transferable. Whether it is appropriate, required or structured in a particular way depends on the project, agreements and regulatory framework. What matters for transparency is that public descriptions of lockups or vesting accurately reflect enforceable arrangements.
Does a smart-contract audit guarantee that the token is safe?
No. An audit reviews a defined scope and version. It cannot guarantee that no vulnerability exists, prevent misuse of administrative privileges, protect a compromised frontend or eliminate operational threats. Security requires continuous controls across contracts, infrastructure, domains, wallets and people.
Can presale funds simply stay in the founder’s wallet?
Doing so can create governance, security, accounting and ownership problems. Project and personal assets should be clearly distinguishable, and treasury authority should correspond to the project’s corporate and governance structure. Appropriate custody and signing arrangements depend on the organization and its obligations.
Can a project promise that its token will be listed on an exchange?
A project should not present an exchange listing as confirmed unless the claim is accurate and authorized. Application, negotiation and preliminary discussion are not necessarily equivalent to a guaranteed listing.
What happens if the token price falls after launch?
Crypto prices can fall significantly, including below presale prices. A sustainable project therefore needs an operating model that does not assume price appreciation. Product development, staffing and treasury planning should be evaluated under adverse market scenarios as well as optimistic ones.
What is the biggest mistake first-time presale founders make?
There is no single universal failure, but a recurring pattern is treating the token sale as the business rather than as one event inside a much larger company-building process. Legal structure, security, product utility, accounting, treasury, compliance and post-launch delivery can matter far more to long-term survival than the mechanics of the sale itself.
The Bottom Line: A Presale Is the Beginning, Not the Business
The easiest part of becoming a crypto presale entrepreneur may be creating the token.
The hard part is building everything around it.
A credible founder needs to understand what is being issued, why it exists, who controls it, how it is sold, which laws may apply, where the proceeds go, how they are protected, what participants are told, what the technology can actually do and what the organization will deliver after the money arrives.
That is why the real presale lifecycle begins long before a “Buy Token” button appears and continues long after the final allocation is sold.
The project starts with a problem worth solving.
It develops into a company with identifiable ownership and responsibilities.
It gains a product architecture.
The token acquires a defined purpose.
Legal and regulatory analysis determines how the project can operate.
Tokenomics define how supply and incentives behave.
Engineering turns the model into software.
Security tries to prevent one bug, one key or one deceptive message from destroying the system.
Compliance controls who can participate and under what conditions.
Accounting tells the organization what happened to the money.
Marketing explains the project without turning ambition into unsupported promises.
Treasury management protects the resources needed to build.
The TGE converts months of promises into an operating token.
Then the founder faces the part that no presale counter can measure: delivering what the project said it would build.
That is the difference between launching a token and building a crypto business.
Anyone considering participation in an early-stage token project should independently verify its legal entity, team, token structure, contracts, security arrangements, disclosures and risks. The Crypto Encounter’s reporting consistently emphasizes that technical security alone does not remove the possibility of scams, operational failures or human error.
This article is provided for informational and educational purposes only. It does not constitute financial, investment, legal, tax, accounting or regulatory advice, nor does it recommend launching, purchasing or participating in any token offering. Crypto assets and early-stage blockchain projects can involve substantial technical, legal, operational, market and loss risks. Applicable rules vary by jurisdiction and can change. Founders and participants should obtain qualified professional advice relevant to their circumstances before acting.